
نوع مقاله : مقاله پژوهشی
چکیده تصویری
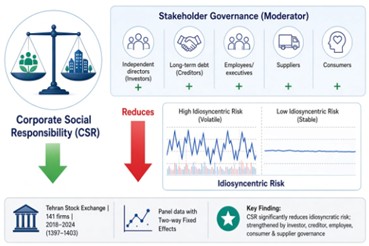
عنوان مقاله English
نویسندگان English
In today’s business environment, corporate responsibility extends beyond profitability and shareholder value creation; firms are also expected to be accountable to society and the environment. Disclosure of corporate social responsibility (CSR) not only contributes to sustainable development but can also reduce idiosyncratic risk. Focusing on stakeholder governance as a moderating variable, this study examines the role of this mechanism in strengthening the inverse relationship between CSR and the reduction of idiosyncratic risk.
The research is applied in terms of purpose and descriptive-correlational in terms of method. The statistical population consists of companies listed on the Tehran Stock Exchange during the period 2018–2024(seven years). Using purposive sampling, 141 companies (987 firm-year observations) were selected as the sample. Required data were collected from the audited financial statements of the companies via the Rahavard Novin software and the CODAL database, and subsequently processed. The research variables were tested using a multivariate regression model and the panel data method with firm and time fixed effects and two-way clustered robust standard errors.
The results indicate that corporate social responsibility has a significant inverse (negative) relationship with idiosyncratic risk; that is, companies with better CSR performance significantly reduce their level of idiosyncratic risk. Moreover, stakeholder governance moderates the relationship between CSR and idiosyncratic risk. In particular, the governance of investors, creditors, employees, and consumers significantly strengthens the positive effect of corporate social responsibility on the reduction of idiosyncratic risk. Supplier governance also shows a significant negative interaction effect, which is discussed in the Iranian institutional context.
کلیدواژهها English

