اقتصاد و سیاست گذاری مالی

اقتصاد و سیاست گذاری مالی

پویایی ارتباطات و سرریز شوک در بازارهای مالی ایران با تأکید بر نقش صندوق‌های درآمد ثابت

نوع مقاله : مقاله پژوهشی

نویسندگان
1 گروه اقتصاد، دانشکده علوم اداری و اقتصادی، دانشگاه فردوسی مشهد، مشهد، ایران
2 گروه اقتصاد، دانشکده علوم اداری و اقتصادی، دانشگاه فردوسی مشهد، مشهد، ایران.
چکیده
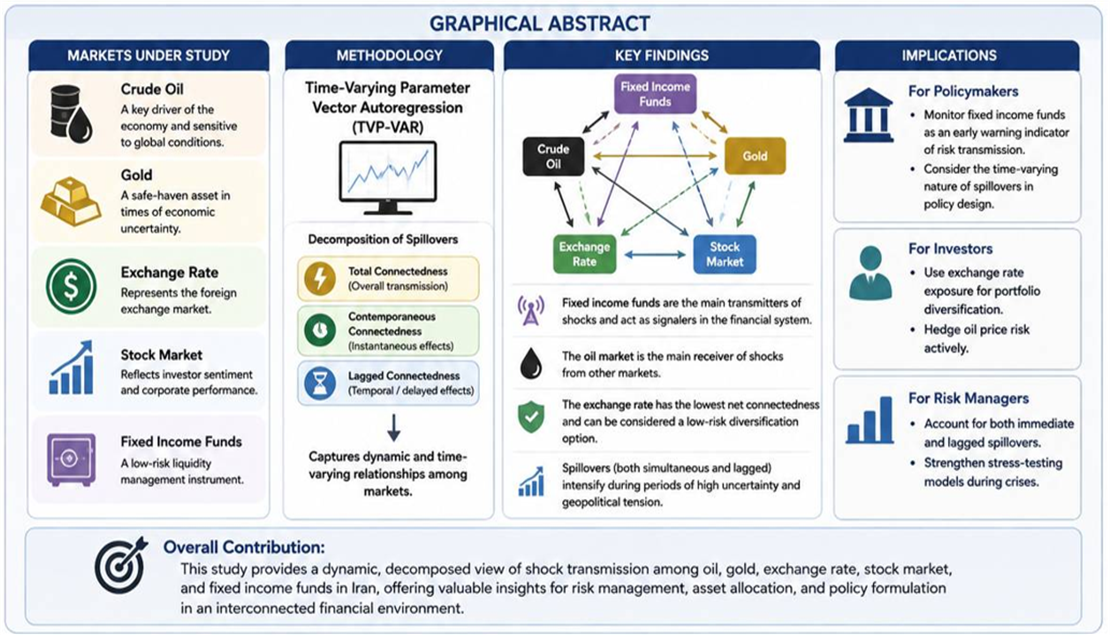
این پژوهش با هدف بررسی پویایی سرریز شوک میان بازارهای نفت، طلا، ارز، سهام و صندوق‌های درآمد ثابت در ایران انجام شده است. برای این منظور، از الگوی خودرگرسیون برداری با پارامترهای متغیر در زمان استفاده می‌شود که امکان تحلیل ارتباطات پویا و متغیر در طول زمان را فراهم می‌سازد. برخلاف رویکردهای سنتی که عمدتاً پیوستگی بازارها را به‌صورت کلی یا ایستا بررسی می‌کنند، این پژوهش با تفکیک سرریزها به ارتباط کل، ارتباط همزمان و ارتباط با وقفه، انتقال آنی و تدریجی شوک‌ها را به‌طور جداگانه ارزیابی می‌کند و هم‌زمان نقش صندوق‌های درآمد ثابت را به‌عنوان یکی از ابزارهای مهم مدیریت نقدینگی در کنار بازارهای دیگر وارد شبکه انتقال ریسک می‌کند. نتایج نشان می‌دهد صندوق‌های درآمد ثابت انتقال‌دهنده اصلی شوک در میان دارایی‌های مورد بررسی هستند و از این منظر نقش سیگنال‌دهنده در بازار ایفا می‌کنند. در مقابل، بازار نفت بیشترین میزان دریافت شوک را از سایر بازارها دارد. همچنین، نرخ ارز به دلیل ارتباط خالص کمتر با سایر اجزای شبکه، می‌تواند گزینه‌ای کم‌ریسک‌تر برای متنوع‌سازی پرتفوی تلقی شود.

چکیده تصویری

پویایی ارتباطات و سرریز شوک در بازارهای مالی ایران با تأکید بر نقش صندوق‌های درآمد ثابت
کلیدواژه‌ها

عنوان مقاله English

Dynamics of Connectedness and Shock Spillovers in Iran’s Financial Markets: Emphasizing the Role of Fixed-Income Funds

نویسندگان English

Farzaneh Ahmadian Yazdi 1
Mozhgan Boroomand Taghizadeh Torbati 2
Amirreza Mohammadi 2
1 Department of Economics, Faculty of Economics and Administrative Sciences, Ferdowsi University of Mashhad, Mashhad, Iran
2 Department of Economics, Faculty of Administrative and Economic Sciences, Ferdowsi University of Mashhad, Mashhad, Iran.
چکیده English

This study aims to investigate the dynamics of shock spillovers among the oil, gold, foreign exchange, stock, and fixed-income fund markets in Iran. To this end, a Time-Varying Parameter Vector Autoregression (TVP-VAR) model is employed, allowing for an analysis of dynamic and time-varying interrelationships among these markets. Unlike conventional approaches that primarily examine market connectedness from an overall or static perspective, this study decomposes spillovers into total, contemporaneous, and lagged connectedness, thereby enabling the separate assessment of the immediate and gradual transmission of shocks. At the same time, fixed-income funds are incorporated into the risk-transmission network as an important instrument for liquidity management alongside other financial markets. The results indicate that fixed-income funds are the primary transmitters of shocks among the assets under investigation and, from this perspective, play a signaling role in the market. In contrast, the oil market exhibits the highest level of shock reception from other markets. Furthermore, given its relatively lower net connectedness with other components of the network, the foreign exchange market may be regarded as a relatively lower-risk option for portfolio diversification.

کلیدواژه‌ها English

Oil
Stock Market
Energy
Foreign Exchange Market
Abarghouei, V. A., Soretz, S., Ahmadian-Yazdi, F., & Mohammadi, A. (2026). Spatial investigation of uncertainty and ecological footprint: A comparative analysis of renewable energy impacts. Journal of Environmental Assessment Policy and Management, 28(1), Article 2650001. https://doi.org/10.1142/S1464333226500018
Aboutorabi, M. A., Ahmadian Yazdi, F., & Parkam, S. (2021). Financial development and natural resource rents–human capital nexus: A new approach. In M. Shahbaz, A. Soliman, & S. Ullah (Eds.), Economic growth and financial development (pp. 33–55). Springer. https://doi.org/10.1007/978-3-030-79003-5_3
Ahmadian-Yazdi, F., Mensi, W., Al-Yahyaee, K. H., Ramsheh, M., & Al-Kharusi, S. (2025). Connectedness between gold, copper, fossil fuels, and major stock markets: Implications for portfolio management. Resources Policy, 109, Article 105728. https://doi.org/10.1016/j.resourpol.2025.105728
Abarghouei, V. A., Soretz, S., Ahmadian-Yazdi, F., & Mohammadi, A. (2026). Spatial investigation of uncertainty and ecological footprint: A comparative analysis of renewable energy impacts. Journal of Environmental Assessment Policy and Management, 28(1), Article 2650001. https://doi.org/10.1142/S1464333226500018
Aboutorabi, M. A., Ahmadian Yazdi, F., & Parkam, S. (2021). Financial development and natural resource rents–human capital nexus: A new approach. In M. Shahbaz, A. Soliman, & S. Ullah (Eds.), Economic growth and financial development (pp. 33–55). Springer. https://doi.org/10.1007/978-3-030-79003-5_3
Ahmadian-Yazdi, F., Mensi, W., Al-Yahyaee, K. H., Ramsheh, M., & Al-Kharusi, S. (2025). Connectedness between gold, copper, fossil fuels, and major stock markets: Implications for portfolio management. Resources Policy, 109, Article 105728. https://doi.org/10.1016/j.resourpol.2025.105728
Ahmadian-Yazdi, F., Salimifar, M., & Ahmadi Shadmehri, M. T. (2015). The impact of trade liberalization and economic growth on non-oil bilateral trade flow between Iran and China over the period 1981–2012. Economic Growth and Development Research, 5(20), 11–30.
Ahmadian-Yazdi, F., Mensi, W., Namazizadeh, E., & Chenarani, H. (2025). Asymmetric connectedness between currency and stock markets and the portfolio analysis implications: Evidence from BRICS economies. Journal of Chinese Economic and Business Studies. Advance online publication. https://doi.org/10.1080/14765284.2025.2601973
Ali, S. R. M., Mensi, W., Anik, K. I., Rahman, M., & Kang, S. H. (2022). The impacts of COVID-19 crisis on spillovers between the oil and stock markets: Evidence from the largest oil importers and exporters. Economic Analysis and Policy, 73, 345–372. https://doi.org/10.1016/j.eap.2021.11.009
Amiri, H., Porjavan, A., & Zahedi, M. (2025). Gold, currency and Bitcoin as hedge or safe haven for stocks: Evidence from Tehran Stock Exchange (TSE) using smooth transition regression (STR) models. Quarterly Journal of Quantitative Economics, 21(4), 220–272.  [In persian]. https://doi.org/10.22055/jqe.2023.39758.2458
Ando, T., Greenwood-Nimmo, M., & Shin, Y. (2022). Quantile connectedness: Modeling tail behavior in the topology of financial networks. Management Science, 68(4), 2401–2431. https://doi.org/10.1287/mnsc.2021.3984
Anscombe, F. J., & Glynn, W. J. (1983). Distribution of the kurtosis statistic for normal samples. Biometrika, 70(1), 227–234. https://doi.org/10.1093/biomet/70.1.227
Arouri, M. E. H., Jouini, J., & Nguyen, D. K. (2011). Volatility spillovers between oil prices and stock sector returns: Implications for portfolio management. Journal of International Money and Finance, 30(7), 1387–1405. https://doi.org/10.1016/j.jimonfin.2011.07.008
Bakas, D., & Triantafyllou, A. (2020). Commodity price volatility and the economic uncertainty of pandemics. Economics Letters, 193, Article 109283. https://doi.org/10.1016/j.econlet.2020.109283
Balli, F., Balli, H. O., Dang, T. H. N., & Gabauer, D. (2023). Contemporaneous and lagged decomposed connectedness approach: New evidence from the energy futures market. Finance Research Letters, 57, Article 104168. https://doi.org/10.1016/j.frl.2023.104168
Batten, J. A., Ciner, C., & Lucey, B. M. (2015). Which precious metals spill over on which, when and why? Some evidence. Applied Economics Letters, 22(6), 466–473. https://doi.org/10.1080/13504851.2014.950789
Baur, D. G., & Lucey, B. M. (2010). Is gold a hedge or a safe haven? An analysis of stocks, bonds and gold. Financial Review, 45(2), 217–229. https://doi.org/10.1111/j.1540-6288.2010.00244.x
Baur, D. G., & McDermott, T. K. (2010). Is gold a safe haven? International evidence. Journal of Banking & Finance, 34(8), 1886–1898. https://doi.org/10.1016/j.jbankfin.2009.12.008
Beckmann, J., & Czudaj, R. (2013). Gold as an inflation hedge in a time-varying coefficient framework. The North American Journal of Economics and Finance, 24, 208–222. https://doi.org/10.1016/j.najef.2012.10.007
Capie, F., Mills, T. C., & Wood, G. (2005). Gold as a hedge against the dollar. Journal of International Financial Markets, Institutions and Money, 15(4), 343–352. https://doi.org/10.1016/j.intfin.2004.07.002
Ciner, C., Gurdgiev, C., & Lucey, B. M. (2013). Hedges and safe havens: An examination of stocks, bonds, gold, oil and exchange rates. International Review of Financial Analysis, 29, 202–211. https://doi.org/10.1016/j.irfa.2012.12.001
D’Agostino, R. B. (1970). Transformation to normality of the null distribution of g1. Biometrika, 57(3), 679–681. https://doi.org/10.1093/biomet/57.3.679
Diebold, F. X., & Yilmaz, K. (2012). Better to give than to receive: Predictive directional measurement of volatility spillovers. International Journal of Forecasting, 28(1), 57–66. https://doi.org/10.1016/j.ijforecast.2011.02.006
Diebold, F. X., & Yilmaz, K. (2014). On the network topology of variance decompositions: Measuring the connectedness of financial firms. Journal of Econometrics, 182(1), 119–134. https://doi.org/10.1016/j.jeconom.2014.04.012
Ding, Q., Huang, J., & Chen, J. (2021). Dynamic and frequency-domain risk spillovers among oil, gold, and foreign exchange markets: Evidence from implied volatility. Energy Economics, 102, Article 105514. https://doi.org/10.1016/j.eneco.2021.105514
Elliott, G., Rothenberg, T. J., & Stock, J. H. (1996). Efficient tests for an autoregressive unit root. Econometrica, 64(4), 813–836. https://doi.org/10.2307/2171846
Fattahi, S., & Nafisi-Moghadam, M. (2023). Do oil sanctions affect the interdependence and integration of financial markets? Heliyon, 9(2), Article e13793. https://doi.org/10.1016/j.heliyon.2023.e13793
Filis, G., Degiannakis, S., & Floros, C. (2011). Dynamic correlation between stock market and oil prices: The case of oil-importing and oil-exporting countries. International Review of Financial Analysis, 20(3), 152–164. https://doi.org/10.1016/j.irfa.2011.02.014
Ha, L. T., & Thanh, T. T. (2025). Measuring dynamic interlinkages between energy uncertainty, investor sentiment and financial market volatility: Fresh insights from the R² decomposed linkage method. Energy Reports, 13, 363–377. https://doi.org/10.1016/j.egyr.2024.11.045
Huang, J., Li, H., Chen, B., Liu, M., An, C., & Xia, X. (2025). Revisiting the currency-commodity nexus: New insights into the R² decomposed connectedness and the role of global shocks. International Review of Economics & Finance, 98, Article 103852. https://doi.org/10.1016/j.iref.2025.103852
Jamshidi, A., Omidi, V., & Ali Karamzadeh, N. (2026). Investigating the spillover effect of stock, currency and coin market fluctuations on social unrest in Iran: An approach of the TVP-QVAR model. Quarterly Journal of Quantitative Economics, 22(4), 127–151. [In persian]. https://doi.org/10.22055/jqe.2024.44036.2562⁠
Jarque, C. M., & Bera, A. K. (1980). Efficient tests for normality, homoscedasticity and serial independence of regression residuals. Economics Letters, 6(3), 255–259. https://doi.org/10.1016/0165-1765(80)90024-5
Jones, C. M., & Kaul, G. (1996). Oil and the stock markets. The Journal of Finance, 51(2), 463–491. https://doi.org/10.1111/j.1540-6261.1996.tb02691.x
Liu, R., Hu, J., Zhang, S., & He, Z. (2024). Risk spillovers among oil, gold, stock, and foreign exchange markets: Evidence from G20 economies. The North American Journal of Economics and Finance, 74, Article 102249. https://doi.org/10.1016/j.najef.2024.102249
Madani, M. A., & Ftiti, Z. (2022). Is gold a hedge or safe haven against oil and currency market movements? A revisit using multifractal approach. Annals of Operations Research, 313(1), 367–400. https://doi.org/10.1007/s10479-021-04288-6
Mensi, W., Al Rababa’a, A. R., Vo, X. V., & Kang, S. H. (2021). Asymmetric spillover and network connectedness between crude oil, gold, and Chinese sector stock markets. Energy Economics, 98, Article 105262. https://doi.org/10.1016/j.eneco.2021.105262
Mensi, W., Reboredo, J. C., & Ugolini, A. (2021). Price-switching spillovers between gold, oil, and stock markets: Evidence from the USA and China during the COVID-19 pandemic. Resources Policy, 73, Article 102217. https://doi.org/10.1016/j.resourpol.2021.102217
Mensi, W., Yousaf, I., Vo, X. V., & Kang, S. H. (2022). Asymmetric spillover and network connectedness between gold, Brent oil, and EU subsector markets. Journal of International Financial Markets, Institutions & Money, 76, Article 101487. https://doi.org/10.1016/j.intfin.2021.101487
Mofid, H., Khosravi-Nikou, M. R., Razavi, S. A., & Mohammadian, M. (2024). Optimization and design selection of a single mixed refrigerant (SMR) liquefaction process for offshore application: A multi-objective approach. Applied Thermal Engineering, 245, Article 122810. https://doi.org/10.1016/j.applthermaleng.2024.122810
Park, J., & Ratti, R. A. (2008). Oil price shocks and stock markets in the U.S. and 13 European countries. Energy Economics, 30(5), 2587–2608. https://doi.org/10.1016/j.eneco.2008.04.003
Razavi, S. A., & Motavali, H. (2023). Project portfolio optimization in upstream oil industry in knowledge-based organization: Case study of Tehran Energy Consultants Company. Journal of Industrial Engineering and Management Studies, 10(2), 106–115. https://doi.org/10.22116/jiems.2023.399150.1516
Razavi, S. A., & Nasr Esfahani, M. (2020). Strategic reflection on the effects of US government policies on the security of Iranian crude oil markets. Political Strategic Studies, 9(35), 101–134. [In persian]. https://doi.org/10.22054/qpss.2020.42777.2320
Razavi, S. A., & Pirani, S. (2019). Energy programs of American parties (Republicans and Democrats) and global oil market. Petroleum Business Review, 3(4), 28–36. https://doi.org/10.22050/pbr.2019.119151
Reboredo, J. C. (2013). Is gold a safe haven or a hedge for the US dollar? Implications for risk management. Journal of Banking & Finance, 37(8), 2665–2676. https://doi.org/10.1016/j.jbankfin.2013.03.020
Roudari, S., Farahanifard, S., Shahabadi, A., & Adeli, O. (2022). Investigating the time-frequency volatility spillover among exchange rate, inflation, stocks and housing prices in Iran. Journal of Economics and Modelling, 13(2), 65–93. https://doi.org/10.48308/jem.2022.228781.1783
Roudari, S., Ahmadian-Yazdi, F., Arabi, S. H., & Hammoudeh, S. (2023). Sanctions and Iranian stock market: Does the institutional quality matter? Borsa Istanbul Review, 23(4), 919–935. https://doi.org/10.1016/j.bir.2023.03.006
Roudari, S., Arabi, S. H., Shahabadi, A., & Adeli, O. (2025). Dynamic spillover of risk between exchange rates, stocks, housing, and gold coins in Iran: New evidence from comparing sanction and non-sanction periods. Journal of Financial Management Strategy, 13(1), 93–116. [In persian]. https://doi.org/10.22051/jfm.2025.41262.2718
Sadorsky, P. (1999). Oil price shocks and stock market activity. Energy Economics, 21(5), 449–469. https://doi.org/10.1016/S0140-9883(99)00020-1
Samadi, A. H., Owjimehr, S., & Nezhad Halafi, Z. (2021). The cross-impact between financial markets, Covid-19 pandemic, and economic sanctions: The case of Iran. Journal of Policy Modeling, 43(1), 34–55. https://doi.org/10.1016/j.jpolmod.2020.08.001
Shakeel, M., Rabbani, M. R., Hawaldar, I. T., Chhabra, V., & Zaidi, F. K. (2023). Is there an intraday volatility spillover between exchange rate, gold and crude oil? Journal of Open Innovation: Technology, Market, and Complexity, 9(3), Article 100094. https://doi.org/10.1016/j.joitmc.2023.100094
Sharif, A., Aloui, C., & Yarovaya, L. (2020). COVID-19 pandemic, oil prices, stock market, geopolitical risk and policy uncertainty nexus in the US economy: Fresh evidence from the wavelet-based approach. International Review of Financial Analysis, 70, Article 101496. https://doi.org/10.1016/j.irfa.2020.101496
Singhal, S., Choudhary, S., & Biswal, P. C. (2019). Return and volatility linkages among international crude oil price, gold price, exchange rate and stock markets: Evidence from Mexico. Resources Policy, 60, 255–261. https://doi.org/10.1016/j.resourpol.2019.01.004
Tok, Ş. A., & Tarkun, S. (2025). Dynamic dependence between sectoral indexes of BRIC countries and the Baltic dirty tanker index: An investigation using the generalized R² approach. Borsa Istanbul Review, 25(2), 265–274. https://doi.org/10.1016/j.bir.2025.01.010
Xu, L., Ma, X., Qu, F., & Wang, L. (2023). Risk connectedness between crude oil, gold and exchange rates in China: Implications of the COVID-19 pandemic. Resources Policy, 83, Article 103691. https://doi.org/10.1016/j.resourpol.2023.103691
Zhu, B., & Woltering, R. O. (2021). Is fund performance driven by flows into connected funds? Spillover effects in the mutual fund industry. Journal of Economics and Finance, 45(3), 544–571. https://doi.org/10.1007/s12197-021-09539-7